Loan Officer Field Guide™
CHIAVAROLI SMITH MEDIA
Loading your desk…
Loan Officer Field Guide | Practice files for new loan officers
Loan Officer Field Guide™Chiavaroli Smith Media™

Scenario-based mortgage training

The first time they see it shouldn’t be on a real file.

For every loan officer: new to the industry, moving between retail, bank and broker, or ready to take on more complex files. And for the managers, mentors and trainers who develop them.

Fifty-seven fictional borrower files. Ask the follow-up question, run the numbers, check the guideline and decide what happens next, before a real borrower is waiting.

Watch first · 2 minutesHow this course worksEllen walks you through it on the real screens: a referred buyer’s first text, the 57 files, your desk, and what a mentor sees.

Now feel it for yourself

One text. 6:42 p.m. A referred buyer is waiting.

What you do in the next hour matters more than you’d think. The free Prologue takes a few minutes, with no account. It’s exactly how every file in the course feels: a real decision, Ellen beside you, and no real borrower on the line.

Start the free PrologueA few minutes · no account · computer, tablet or phone

Then pick your path

Where are you coming from?

The habit behind every file

Reported. Open. Documented. Verified.

In every file, each fact gets one of four tags, based on what you can prove right now. It’s how underwriters already think, and it’s the habit that keeps a loan officer from quoting a number that falls apart later.

Here’s a practice file from later in the course. Watch Ellen explain the tags, or open the key to see each one.

A PRACTICE FILE · NINA & THEO CASTELLANOFICTIONAL
  1. CallNINAI make about $90,000 a year.R
  2. CallTHEOI also do some freelance design on the side.O
  3. DocCREDIT REPORTAuto loan · $412 a month · 31 payments leftD
  4. DocPAYSTUBS + W-2sNina’s overtime: two steady years, and the guideline lets you count itV

R ReportedO OpenD DocumentedV Verified

What do R, O, D and V mean, and why tag at all?

We use four working labels to track what we know and what still needs checking. The label tells you what you can say to the borrower now, what goes on your needs list, and what you’d stand behind in a preapproval.

R Reported
Someone told you. It’s their word, not proof yet, so note who said it and when. Nina says she makes “about $90,000.” Her word, for now.
O Open
You can’t settle it yet: a document is missing, or two sources disagree. It goes on the needs list. Theo mentions freelance design. Until you see his tax returns, you don’t know what, if any of it, counts.
D Documented
A specific, named document shows it: a paystub, W-2, bank statement or credit report. It proves the fact exists, not that it counts. Their $412 car payment, right there on the credit report.
V Verified
You checked the documented fact against what decides it, the agency guideline, the AUS findings and the lender’s overlays, and it holds. Nina’s overtime: two steady years on her paystubs and W-2s, and the guideline lets you count it. The underwriter still makes the final call when they clear the condition.

Underwriters already think this way. Loan officers who do too quote numbers that hold up and get fewer surprise conditions. In Chapter 1 you’ll tag the facts in Chloe’s fictional file yourself.

Each fact is tagged by what you can prove right now. Ellen’s rule: tell a borrower or an agent only what you’d stand behind.

Ellen Quinn, fictional mentor
Meet Ellen QuinnYour fictional mentor · veteran loan officer

She runs the team you join on day one and stays beside you through all fifty-seven files. She tells you why she asked each question, catches the number that’s wrong, and explains the rule instead of just citing it.

It isn’t talent.
It’s the gap.

The gap between passing the licensing test and knowing what to do with your first borrower file.

Try one · Ellen’s first question for you

NINA & THEO · first call“We want to stay around $2,000 a month. Oh, and Theo’s about to sign for a truck, around $400 a month.”

Step 1 of 2 Lenders cap total monthly debts as a share of income, so every dollar of truck payment is a dollar that can’t go to the house. About how much less can they borrow because of the truck?

What a monthly payment carries30-year fixed at 7% · principal and interest onlyIllustration
Monthly paymentLoan it carries
$100→about $15,000
$2,000→about $300,600

What changes

What a new loan officer can do after

  1. The Prologue · a few minutes · freeAnswer a referral the same night.

    They reply to a 6:42 p.m. text from a referred buyer, keep the agent in the loop and set a callback time instead of going quiet.

  2. Chapter 1 · about 90 minutes · free by requestSeparate what the borrower said from what’s proven.

    They label each fact Reported, Open, Documented or Verified, catch a paycheck that doesn’t match what the borrower said, and count a debt that isn’t on the credit report.

  3. Chapters 1–5Work a purchase to closing, then the hard calls.

    One buyer from preapproval through contract, appraisal, conditions and closing week. Then variable nurse pay, a payment reality check with two loans side by side, and a bankruptcy “not yet” turned into a date and a plan.

What’s inside

Practice the decisions new loan officers need to learn.

57 practice files

Fictional borrowers in ten states, each worked one decision at a time.

  • First-time buyers, refinances and second homes
  • FHA, VA, USDA and conventional, including down payment help
  • Self-employed, commission, bonus and variable pay
  • Divorce, bankruptcy, foreclosure and credit rebuilding
  • Condos, appraisals, conditions and closing week
A desk to work from

The tools a new loan officer keeps using after the lesson ends.

  • Today: the day’s calls, follow-ups and habits
  • My Desk: tasks, notes and the files in progress
  • Rule cards, each linked to its agency source
  • Build Your Book: the referral and follow-up rhythm
  • Real Life lessons that set up their actual desk
A mentor view

For the person who signs off on a new loan officer’s first files.

  • Progress through each chapter and lesson check
  • Each skill: right the first time, after a hint, or still needs review
  • Written answers, ticked against Ellen’s checklist, to review and mark
  • Real Life setup steps, like lender logins, still to schedule

Work a practice file

One file, one step at a time.

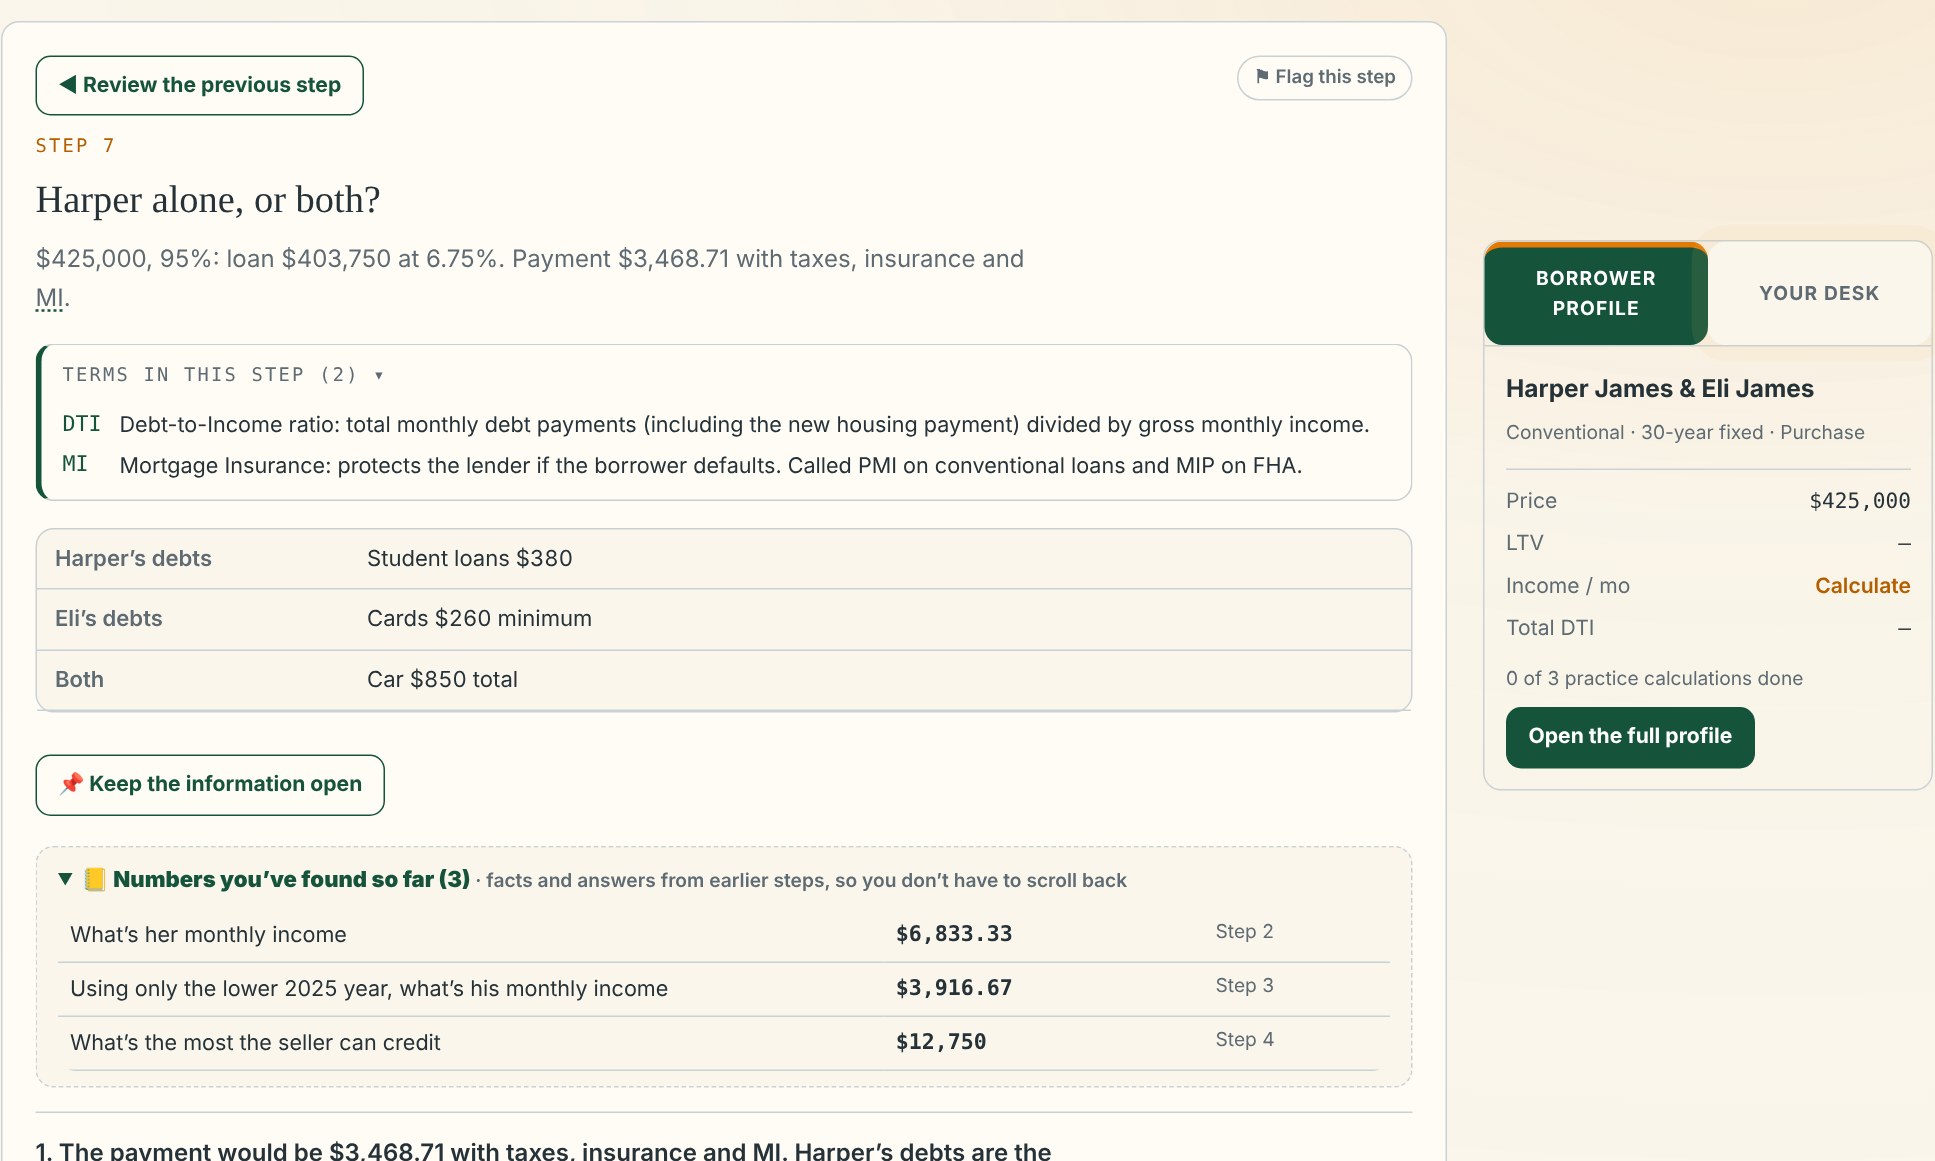
Each step brings only what you need, the lines from the call, the document or the rule, and you answer to unlock the next.

A lesson step from Chapter 17, with the borrower profile beside itClick to enlarge

Borrower profile

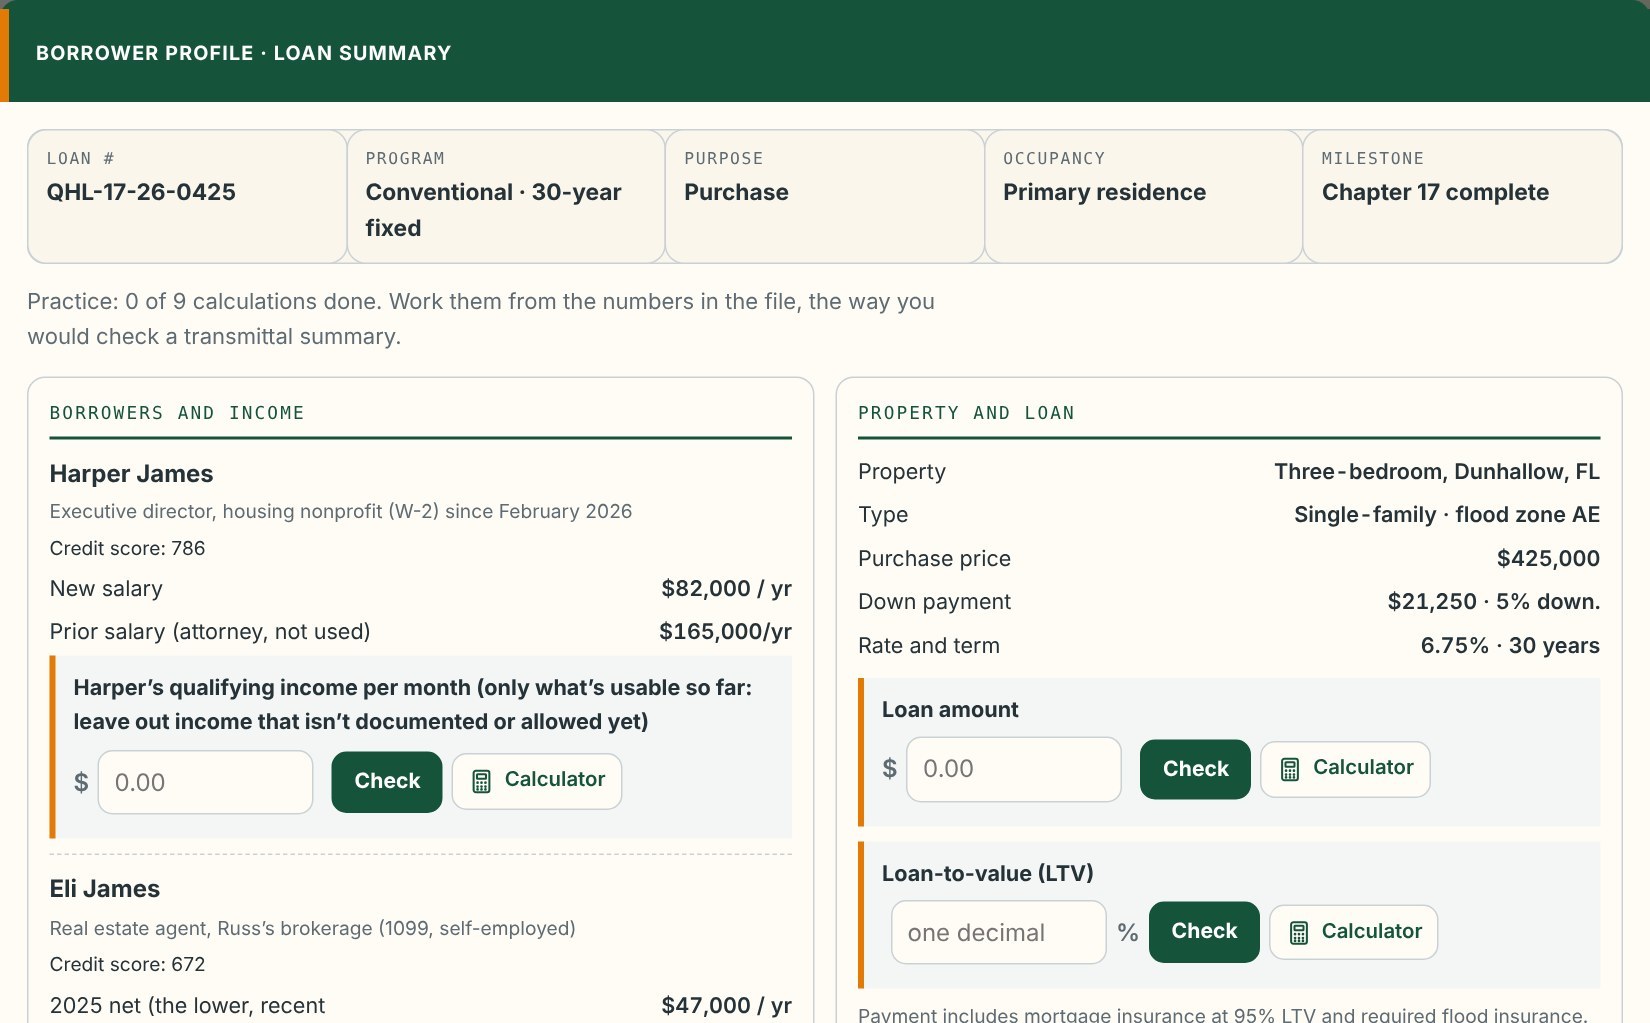
The whole file on one screen, like a lender portal.

The numbers fill in only after you’ve earned them in the lesson.

The borrower profile with practice calculationsClick to enlarge

Meet the people you’ll serve.

Teachers, nurses, veterans, surgeons, contractors, retirees and first-time buyers in ten states. Fictional people with real problems.

Course overview

Who built it
Kimberly Smith

Kimberly Smith

Co-founder · Educator turned originator

Nearly two decades teaching middle school math and leading teacher development, then a loan officer since 2016 and a mortgage broker since 2023. She builds each chapter the way she built lessons: small steps, practice before pressure.
Clayton Chiavaroli

Clayton Chiavaroli

Co-founder · Originating since 2003

Originating since 2003 at small mortgage companies, a community bank, national retail lenders and now as a broker. He knows how the work looks from each side of the desk, and how much of it nobody explains to new loan officers.

More about the founders

The borrower knows exactly how much they make. Payroll may have additional information.

Loading the syllabus…

Course overview

Practice the decisions before the stakes are real.

Watch first · 2 minutes

How this course works

Ellen walks you through it on the real screens: the Prologue text, the 57 files, labeling what you know, hints and answers, writing in your own words, a practice call, your desk, and what a mentor sees.

A prologue, then fifty-seven borrower files (fifty chapters and seven bonus files): forty-nine borrowers whose lives keep moving. Some files are one borrower. Others are a married couple, unmarried partners, or a college student whose parents are helping.

And borrowers come back.

  1. A divorce turns one household into two separate files.
  2. A first-time condo buyer relocates and keeps the condo as a rental.
  3. A retiree returns newly widowed, on a smaller income, with grown children who disagree.
  4. A buyer who needed a co-signer refinances to stand on her own.
  5. Two partners with a house each build one together.

SyllabusCourse mapReal lead? Start here

  1. Hear the borrower

    Read a veteran loan officer’s first call and see why she asked each question. Sort what the borrower said from what still needs a document.

  2. Check the file

    Open the paystubs, returns, statements and credit report. Compare what the borrower said with what the file shows, and look up the guideline.

  3. Run the numbers

    As you answer, the borrower profile fills in like a lender portal. Work out income, loan-to-value (LTV) and debt-to-income (DTI) by hand, then check them against the loan’s summary.

  4. Choose what to say

    Pick the next step and the words for the borrower or the agent: an honest status, the open items, and no promise you can’t keep. Every answer comes with the reason.

How each chapter works
  • Phases unlock in order: no documents until the intake is done
  • Every acronym defined where it appears, and a calculator beside every number question
  • A hint after a wrong answer, the reason behind every right one, and the answer itself after three misses
  • Works on a computer, tablet or phone, and saves to your account

What this isn’t. The Field Guide doesn’t replace company training, official guidelines, underwriting, compliance, licensing education or supervision. Current agency, investor and lender guidelines always control.

Label every fact
RReportedSomeone said it: the borrower, an agent, anyone. Note who and when.
OOpenYou can’t settle it yet: an answer, a document or a rule is missing, or two sources disagree.
DDocumentedA named record shows it. Cite the page.
VVerifiedChecked against what decides it (the agency guideline, AUS findings and lender overlays), and it holds. The underwriter still makes the final call.
Works in any state
Works across states

Most of what you practice comes from agency and federal guidelines

Fannie MaeFreddie MacFHAVAUSDATRID and RESPAFair lending (ECOA)
Changes at the state line

Taught as a lookup, with who to ask

  • Who conducts the closing
  • Who must sign
  • What recording costs
  • What a condo buyer is owed
What the course covers
Example chaptersAll 57 files

Prologue · Can We Chat?

Day one. Your phone buzzes.

You just joined Ellen Quinn’s team at Quillmark Home Lending. You’re licensed. Nobody has told you what to do next. Then a text comes in.

Your mentor

Ellen Quinn

She is the veteran loan officer whose team you just joined, and she stays beside you through all fifty-seven files. She does not do the work for you. She tells you why she asked a question, catches you when a number is wrong, and explains the rule instead of just citing it. Miss something once and she gives you a hint; miss it three times and she shows you the answer and the reasoning behind it.

Start here. Everything you pick up in the next few minutes — the contact, the reminder, the habit — moves onto your desk and carries into Chapter 1.

“My team’s in Massachusetts, so our first few borrowers are local. Almost everything you’ll learn works the same in every state. When something is a Massachusetts thing, I’ll say so and show you how to look it up for yours.” Ellen

Ellen and every borrower in the course are fictional. The situations are not.

Start
0practice points

Chapter 1 · The First Conversation · Phases 1–3

New here? Start with the Prologue first — it takes a few minutes and sets up your desk.

Your first borrower. Your first week on Ellen’s team.

Ellen Quinn, a veteran loan officer, just finished a call with a referred buyer named Chloe, and she’s handing you the file. Read the conversation once. Then work through it one step at a time. Every right answer unlocks the next step, and every new tool, person and system goes onto your desk.

Chloe Nguyen, fictional borrower
Chloe NguyenBorrower · 29 · first-time buyer
Talia Brennan, fictional real estate agent
Talia BrennanChloe’s real estate agent
Ellen QuinnYour mentor · veteran loan officer

All characters, their portraits and financial records are fictional training material.

What to watch

  • Every fact starts as Reported — something someone said. It becomes Documented when a named document shows it and Verified when a second source or the guideline confirms it. What is still Open stays visible.
  • The learner does the arithmetic. A wrong number has to be corrected before the file moves on.
  • Miss once and the mentor gives a hint. Miss three times and she shows the answer and the reasoning behind it.
  • The file fills in only as the learner earns it. Nothing is handed over.
Start
0score so far / 100
0badges

That is the sample

Chapter 1 is the rest of this file, from the first conversation to a clear next step.

Request Chapter 1About the free preview

A short form. It goes straight to the two of us.

Chapter 2 · Chloe, from preapproval to keys · Phases 1–3 · approved draft

Same borrower. Now get her to the closing table.

Chloe’s follow-up documents are in and her application has been reviewed. Now settle the open items, write a preapproval Talia can trust, get through the contract deadlines, a condo review, a low appraisal and closing week.

Chloe Nguyen, fictional borrower
Chloe NguyenBorrower · 29 · first-time buyer
Talia Brennan, fictional real estate agent
Talia BrennanChloe’s real estate agent
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Chloe’s documents for this chapter are in her case file in the Field Kit. New here? Start with Chapter 1.

Chapter 3 · Sofia Alvarez · Phases 1–3 · complete draft

A nurse whose paychecks never look the same.

Chloe sends you her first referral: Sofia, an ICU-tough nurse who wants to buy on her own while her boyfriend helps with bills. Her overtime is shrinking, her differential stopped, and her score is two points from a pricing tier.

Sofia AlvarezBorrower · 29 · RN · first-time buyer
Chloe NguyenPast client · referred Sofia
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 4 · Maya Chen · Phases 1–3 · complete draft

A teacher, a block house and a Florida reality check.

Russ Halvorsen, a veteran Gulfshore County agent, sends Ellen a buyer: Maya Chen, a seventh-grade math teacher who wants a modest single-family home before winter break. Ellen is licensed in Florida too, and she takes the call while you listen in. Then you work the file.

Maya ChenBorrower · 34 · teacher · first-time buyer
Russ HalvorsenMaya’s agent · Gulfshore County · 25+ years
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material.

Chapter 5 · Kelsey Brown · Phases 1–3 · complete draft

It’s not no. It’s not yet.

Russ sends you Kelsey, a hospital administrator with a 2024 bankruptcy, a 557 score and a perfect mortgage history. The right answer today is a plan, not a loan. How you say it decides whether she comes back.

Kelsey BrownBorrower · 43 · hospital administrator
Russ HalvorsenAgent · referred Kelsey
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 6 · Darius King · Phases 1–3 · complete draft

A paratrooper, a firehouse and a garage.

Kelsey, your readiness client, sends you Darius: a firefighter/paramedic whose overtime rivals his salary, who hates paperwork, and who almost forgets to mention six years in the Army.

Darius KingBorrower · 39 · firefighter/paramedic · veteran
Kelsey BrownReferred Darius
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 7 · Daniel Ortiz · Phases 1–3 · complete draft

One monster year is not an average.

Talia sends you her cousin in Silvermere, Oregon: Daniel, a fast-moving sales manager fresh off a huge commission year. He wants a number now. His weak year, his child support and a house sale that hasn’t closed say: not yet.

Daniel OrtizBorrower · 41 · sales manager
Talia BrennanMassachusetts agent · referred her cousin Daniel
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 8 · Owen Murphy · Phases 1–3 · complete draft

He wrote $214,000. The IRS saw less.

Russ sends you Owen, his go-to insurance broker. Owen wants to keep the house in his divorce, quotes his gross commissions and promises documents “this weekend.”

Owen MurphyBorrower · 57 · self-employed insurance broker
Russ HalvorsenAgent · referred Owen
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 9 · Grace Kim · Phases 1–3 · complete draft

The easiest file, until it isn’t.

Sofia sends you her coworker Grace, a pharmacist with a spreadsheet, a 795 score and a husband who teaches chemistry. Their only question: sell the condo or keep it as a rental?

Grace KimBorrower · 31 · pharmacist
Andrew KimCo-borrower · high school teacher
Sofia AlvarezPast client · referred Grace
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 10 · Caleb Reed · Phases 1–3 · complete draft

The tenants pay the mortgage. Allegedly.

Grace’s cousin Caleb has found a Kentham triple-decker and watched a lot of house-hacking videos. He has $14,000, a big truck payment and a friend who “might go in on it.”

Caleb ReedBorrower · 22 · junior civil engineer
Grace KimCousin · referred Caleb
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 11 · Brenda Lawson · Phases 1–3 · complete draft

Her house. Her choice.

Maya sends you Brenda, her former assistant principal: widowed, 67, in a paid-off Seagrape house that’s too big. Her brother has opinions. Your job is options, including doing nothing.

Brenda LawsonBorrower · 67 · retired school administrator
Maya ChenPast client · referred Brenda
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 12 · Lena Park · Phases 1–3 · complete draft

No score is not bad credit.

Chloe sends you a coworker who works remotely from Mistral Falls, Montana: Lena, 24, who has never had a credit card. She pays rent by check, has $9,000 saved, and a family friend offering to co-sign.

Lena ParkBorrower · 24 · marketing coordinator
Chloe NguyenPast client · referred Lena
Camille DuboisFamily friend · offered to co-sign
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 13 · Marcus & Renee Reed · Phases 1–3 · complete draft

A contractor, a shoebox and a jumbo loan.

Caleb’s uncle Marcus builds houses for a living and keeps his paperwork in a shoebox. His wife Renee keeps everything else. Their $1.25 million colonial is jumbo territory.

Marcus ReedBorrower · 46 · S-corp owner, contractor
Renee ReedCo-borrower · operations director
Caleb ReedNephew · referred Marcus
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 14 · Priya Nair · Phases 1–3 · complete draft

Two Loan Estimates, line by line.

Sofia’s coworker Priya brings your Loan Estimate and a competitor’s, and wants every line explained. The fair answer earns her trust.

Priya NairBorrower · 38 · physical therapist
Dev NairCo-borrower · software QA
Sofia AlvarezPast client · referred Priya
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 15 · Elena Torres · Phases 1–3 · complete draft

PCS orders and a VA loan still open.

Darius sends you Captain Elena Torres, moving to MacDill with a VA loan still open on her old house. Entitlement math decides how much she can borrow with nothing down.

Capt. Elena TorresBorrower · 36 · Army logistics officer
Luis TorresSpouse · works remotely
Darius KingPast client · referred Elena
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 16 · Jamal Washington · Phases 1–3 · complete draft

Separated, not yet signed.

Talia sends you her old college friend Jamal, now in Dellmont, Georgia, a police officer who doesn’t trust banks. He wants a place for his kids, but he’s still on the house with his wife, and nothing’s signed.

Jamal WashingtonBorrower · 44 · police officer
Talia BrennanAgent · referred her college friend Jamal
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 17 · Harper & Eli James · Phases 1–3 · complete draft

The agent is the buyer.

Eli sells houses at Russ’s brokerage. Now he and Harper are buying one: her salary just dropped by half on purpose, his commissions fell, and his credit card habits show.

Eli JamesBorrower · 37 · real estate agent
Harper JamesCo-borrower · nonprofit director
Russ HalvorsenEli’s broker · referred them
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 18 · Nia Okafor · Phases 1–3 · complete draft

A comparison, not a pitch.

Priya sends you Dr. Nia Okafor, a surgeon she worked with in Bayport who now co-owns a practice in Carrow, North Carolina, with $310,000 in student loans, strong assets and a preference for keeping cash. Physician loan or jumbo?

Dr. Nia OkaforBorrower · 45 · surgeon, practice owner
Priya NairPast client · referred Nia
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 19 · Walter Lawson · Phases 1–3 · complete draft

Kind and fast. Mostly fast.

Brenda’s brother Walter wants a $1.1 million Gulf-view condo in a tower that’s barely started selling. His income is fine. The building may not be.

Walter LawsonBorrower · 73 · retired physician
Brenda LawsonSister · past client
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 20 · Samir & Mariam Haddad · Phases 1–3 · complete draft

New to U.S. credit, in order.

Mariam, a dentist who once tutored Lena in college chemistry, and her husband Samir, an engineer on an H-1B visa with no U.S. score, want a Vista Serena townhouse in Solana County. Part of their down payment is still overseas.

Dr. Mariam HaddadBorrower · 29 · associate dentist
Samir HaddadCo-borrower · 30 · mechanical engineer
Lena ParkPast client · referred them
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 21 · Aisha Rahman · Phases 1–3 · complete draft

Fourteen tabs and three jobs.

Samir’s former coworker Aisha has a spreadsheet for everything: three jobs in three years, new RSUs and $86,000 in vested shares.

Aisha RahmanBorrower · 27 · software engineer
Samir HaddadPast client · referred Aisha
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 22 · Ethan Brooks · Phases 1–3 · complete draft

Buying before selling.

Marcus sends you Ethan, an executive who found a $1.6 million house before selling his own. Four ways to bridge the gap, each with a price.

Ethan BrooksBorrower · 52 · operations executive
Marcus ReedPast client · referred Ethan
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 23 · Tyler Brooks · Phases 1–3 · complete draft

On-target isn’t on paper.

Ethan’s son Tyler left teaching for pharma sales four months ago and moved to Nashford, New Hampshire. He’s counting commission he hasn’t earned, and he doesn’t want his dad to know about May.

Tyler BrooksBorrower · 28 · pharma sales rep
Ethan BrooksFather · past client
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 24 · Noah Bennett · Phases 1–3 · complete draft

A backyard apartment for the grandkids.

Brenda’s friend from her old church in Maine, Noah, wants to build an apartment behind his rural Stanhope Lake home for his daughter’s family. He’s trusting, prefers mail, and someone has offered to “handle the paperwork.”

Noah BennettBorrower · 63 · retired municipal employee
Brenda LawsonPast client · Florida · referred Noah
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 25 · Andre & Natalie Coleman · Phases 1–3 · complete draft

Keep it in the family.

Jamal sends you Andre, who inherited a third of his mom’s Dorrance two-family. His sisters want out. He and Natalie want to buy them out.

Andre ColemanBorrower · 49 · union electrical foreman
Natalie ColemanCo-borrower · HR director
Jamal WashingtonPast client · referred Andre
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 26 · Victor Petrov · Phases 1–3 · complete draft

Paper, or more paper.

Walter’s favorite restaurant owner, Victor, makes more than his returns show, keeps cash in a safe, and finds U.S. paperwork baffling.

Victor PetrovBorrower · 42 · restaurant owner
Walter LawsonPast client · referred Victor
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 27 · Camille Dubois · Phases 1–3 · complete draft

Under-promise, over-deliver.

Lena’s godmother Camille, a financial planner with three rentals, wants a cash-out refinance in 21 days. Her other lender promised ten.

Camille DuboisBorrower · 55 · financial planner
Lena ParkGoddaughter · past client
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 28 · Henry Wallace · Phases 1–3 · complete draft

Never too late.

Maya’s school volunteer Henry is a 71-year-old Navy veteran who never used his VA benefit. His wife likes money in the bank.

Henry WallaceBorrower · 71 · retired business owner, Navy veteran
Maya ChenPast client · referred Henry
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 29 · Monica Ellis · Phases 1–3 · complete draft

A refinance a CPA can audit.

Owen’s CPA Monica needs to refinance to pay her ex-husband his share within 180 days, and she wants a citation for every rule.

Monica EllisBorrower · 51 · CPA practice owner
Owen MurphyPast client · referred Monica
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 30 · Trevor Ellis · Phases 1–3 · complete draft

Slow down to speed up.

Monica’s ex, Trevor, wants to buy the day his buyout arrives, with a 618 score and a plan to put part of the down payment on a credit card advance.

Trevor EllisBorrower · 53 · medical-device sales
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 31 · Miguel Santos · Phases 1–3 · complete draft

A seller credit is a design problem.

Russ sends you Miguel, an architect with a clean file, a 1950s ranch and a $12,000 seller credit. Closing costs, a permanent buydown or a 2-1?

Miguel SantosBorrower · 40 · architect
Russ HalvorsenAgent · referred Miguel
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 32 · Tessa Morgan · Phases 1–3 · complete draft

Opening the envelope.

Lena sends you Tessa, a freelance designer who avoids bad news and hasn’t checked her credit in years. It’s 584.

Tessa MorganBorrower · 33 · freelance designer
Lena ParkPast client · referred Tessa
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 33 · Arjun & Neha Mehta · Phases 1–3 · complete draft

Can vs. should.

Nia sends you the Mehtas: six financed properties, $2.8 million in balances and a lake house. Arjun expects exceptions. Neha asks whether they should.

Arjun MehtaBorrower · 48 · tech entrepreneur
Neha MehtaCo-borrower · professor and consultant
Nia OkaforPast client · referred the Mehtas
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 34 · Leila Mehta · Phases 1–3 · complete draft

The driver’s seat.

The Mehtas’ daughter Leila is 20 and wants a condo near campus. Her parents will help. She didn’t know she could be the buyer.

Leila MehtaBorrower · 20 · student and intern
Arjun & Neha MehtaParents · past clients
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 35 · Patrick & Denise O’Neal · Phases 1–3 · complete draft

Shown, not told.

Marcus sends you Patrick, who’s heard five banks say they know their stuff, and Denise, who keeps the books. A sixth rental, two ways.

Patrick O’NealBorrower · 58 · HVAC/plumbing owner
Denise O’NealCo-borrower · bookkeeper
Marcus ReedPast client · referred the O’Neals
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 36 · Frank & Linda DeLuca · Phases 1–3 · complete draft

Nothing left out.

Patrick sends you Frank, who runs three auto-repair companies, mixes business and personal money, and wants you to “leave some of that out.” Linda keeps the records.

Frank DeLucaBorrower · 62 · auto-repair owner
Linda DeLucaCo-borrower · office manager
Patrick O’NealPast client · referred Frank
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 37 · Raymond & Evelyn Greene · Phases 1–3 · complete draft

Advice first.

Noah sends you the Greenes. Raymond doesn’t want a loan. Evelyn worries about the bathtub. The roof is from 1998. The best answer may be no loan.

Raymond Greene76 · retired postal worker
Evelyn Greene74 · retired homemaker
Noah BennettPast client · referred the Greenes
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 38 · Jordan Price · Phases 1–3 · complete draft

Cite it.

Priya sends you Jordan, a fintech analyst in a divorce who has read the Selling Guide and insists her new alimony counts. It doesn’t, yet.

Jordan PriceBorrower · 32 · fintech analyst
Priya NairPast client · referred Jordan
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 39 · Kayla Price · Phases 1–3 · complete draft

Moving out.

Jordan’s little sister Kayla is a school aide with a 612, $6,000 saved and a strong need to leave her parents’ house. Jordan might co-sign.

Kayla PriceBorrower · 25 · school aide
Jordan PriceSister · possible co-signer
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 40 · Robert & Michelle Sinclair · Phases 1–3 · complete draft

An honest loss, maybe.

Camille sends you Robert, a bank executive whose bank gives him a rate discount, and Michelle, whose design firm he forgets to mention. You might lose this one, honestly.

Robert SinclairBorrower · 50 · bank executive
Michelle SinclairCo-borrower · design firm owner
Camille DuboisPast client · referred the Sinclairs
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 41 · Lauren Bishop · Phases 1–3 · complete draft

Recovering, not ruined.

Monica sends you Lauren, a COO whose ex let the old mortgage go 30 days late during their divorce. She’s rewritten her question four times.

Lauren BishopBorrower · 43 · small-business COO
Monica EllisPast client · referred Lauren
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 42 · George Whitaker · Phases 1–3 · complete draft

Generations.

Robert Sinclair sends you George, 82, who wants to help his granddaughter buy a condo without selling investments. Gift, co-sign, buy it himself or lend?

George Whitaker82 · retired executive
Emma WhitakerGranddaughter · 27 · nurse
Robert SinclairPast client · referred George
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 43 · Chloe Nguyen, returns · Phases 1–3 · complete draft

Licensed where it counts.

Two years after Chapter 2, Chloe is moving to Cedar Hollow. She wants to keep her condo and buy in Texas. Ellen isn’t licensed there.

Chloe NguyenPast client · 28 · product manager
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 44 · Kelsey Brown, returns · Phases 1–3 · complete draft

Not yet is now.

March 2028. Four years since Kelsey’s discharge, her score is 702, and Russ found her a house in Clearhaven.

Kelsey BrownPast client · 45 · hospital administrator
Russ HalvorsenAgent
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 45 · Darius King & Miguel Santos · Phases 1–3 · complete draft

Blueprint.

Darius and Miguel, both past clients, are building a custom home on Miguel’s lot. One construction loan, two current houses and a title question for an attorney.

Darius KingPast client · firefighter/paramedic
Miguel SantosPast client · architect
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 46 · Evelyn Greene, returns · Phases 1–3 · complete draft

Her pace.

After Raymond’s death, Evelyn calls Ellen. Her income has dropped, her children disagree, and she’d like to stay.

Evelyn Greene76 · widowed
Noah BennettFriend
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 47 · Kayla Price, returns · Phases 1–3 · complete draft

Solo.

Kayla is a certified teacher now, on time, and ready to take her sister off the loan.

Kayla PricePast client · 27 · teacher
Jordan PriceSister · co-borrower
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 48 · Owen Murphy, returns · Phases 1–3 · complete draft

Clean hands.

Owen has sent you six clients and wants $250 for every one that closes. Then he suggests a “marketing fee.”

Owen MurphyReferral partner
Russ HalvorsenAgent
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 49 · Walter Lawson, returns · Phases 1–3 · complete draft

Concrete facts.

Walter wants cash out of his 1978 Clearhaven Beach condo. The building’s milestone inspection found $3.4 million in concrete repairs.

Walter LawsonPast client · 75
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

Chapter 50 · Capstone · approved draft

It’s your desk now.

Ellen is out for the day and hands you her desk: five calls before 9 a.m., from people you know, and one stranger who wants a rate.

Ellen QuinnOut today
Alex MorenoNew lead · no referral
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. Approved by the founders as a working draft. Rules and numbers are verified before public launch.

My Desk

Field Kit

Chloe’s complete case file, ready the moment a lesson calls for it.

Chloe’s case file opens page by page, one phase at a time. It’s practice with a course borrower. Real borrowers belong in your company’s LOS and CRM, never on this site.

Chloe’s case file · one phase at a time

Chapter 1 opens each document inside the lesson when you need it. Here is the whole file for review. Tap any page to read it full size.

The documents will wait. They have nowhere else to be.

Instructors and mentors: the instructor edition with the full answer key is shared separately. Ask the Field Guide team. Every borrower, building and record here is fictional. The condo-research record is modeled on a real HUD lookup so you can practice reading one.

My Plan

Your business, your life, your plan.

It starts with a few questions and grows with you: your vision, a private journal, quarterly reviews and an honest look at what’s working. Answer a little at a time, whenever you’re ready.

✦ My Why

What you’re doing this for.

Where you came from, what you’re doing this week and where you’re going, in one private place. Start with one sentence.

Bonus chapter 51 · Brianna & Corey Holloway · Phases 1–3 · new draft

Everyone under the roof.

Dr. Nia Okafor sends you Brianna Holloway, a medical assistant at her Carrow practice. Brianna and her husband Corey want a $280,000 ranch on a well and septic in rural Unity County, with nothing down, and her mom is moving in with them. USDA?

Brianna HollowayReferred by Dr. Nia Okafor · 29 · medical assistant
Corey HollowayHusband · co-borrower · HVAC technician
Loretta PruittBrianna’s mother · household member, not a borrower
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. New draft for the founders’ review. Rules and numbers are verified before public launch.

Bonus chapter 52 · Ana & Jesse Lindgren · Phases 1–3 · new draft

Two acres and a data plate.

Lena Park sends you her neighbors from across the hall in Mistral Falls: Ana and Jesse, who want a 2003 double-wide on two acres outside Hollis Creek. It has a well, a septic system and a vehicle title.

Ana LindgrenBorrower · 32 · pharmacy technician
Jesse LindgrenCo-borrower · 34 · utility meter tech
Lena ParkPast client · referred Ana and Jesse
Hollis TateMontana-licensed engineer
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. New draft, pending the founders’ review. Rules and numbers are verified before public launch.

Bonus chapter 53 · Nate Kowalski · Phases 1–3 · new draft

Red flags, gently.

Owen Murphy sends you Nate, the son of a longtime insurance client: a likable first-time buyer with a 21-day deadline, a paystub that doesn’t add up and a “gift” that comes with a payment plan.

Nate KowalskiBorrower · 29 · logistics coordinator
Owen MurphyReferral partner · referred Nate
Dale HurleySeller’s brother
Ellen QuinnYour mentor · veteran loan officer

All characters and records are fictional training material. New draft, pending the founders’ review. Rules and numbers are verified before public launch.

Chapter 54 · Imani Pryor · Phases 1–3 · new draft

One No, Three Lenders

Sofia Alvarez sends her coworker Imani, a respiratory therapist declined online for an FHA purchase in Brackley Falls. FHA allows her 648 score and 49% DTI. The question is which lender will, at what total cost, before the November 25 commitment.

Imani PryorBorrower · respiratory therapist, first-time buyer
Sofia AlvarezReferrer · past client, nurse at the same hospital
Bettina ChoImani’s buyer’s agent
Corinne VanceAE · Larkspur Wholesale
Wes OkonjoAE · Copperleaf Wholesale
Simone VargaAE · Wrenfield Lending
Ellen QuinnYour mentor · veteran loan officer

All characters, lenders and records are fictional training material. New draft, pending the founders’ review. Rules and numbers are verified before public launch.

Chapter 55 · Lucia & Javier Ortega · Phases 1–3 · new draft

Short sale, then as-is

Russ Halvorsen sends a couple with a signed short-sale offer in Larkmoor. When the seller’s lender counters out of reach, they pivot to a bank-owned house with the water off and four required repairs.

Lucia OrtegaBorrower · dental office manager, $52,000
Javier OrtegaCo-borrower · HVAC service tech, $58,000
Russ HalvorsenBuyers’ agent · veteran Gulfshore County agent
Wanda KesslerListing agent · the short sale, then the bank-owned house
Gil NavarroTitle agent · Pelican Park closing
Ellen QuinnYour mentor · veteran loan officer

All characters, lenders and records are fictional training material. New draft, pending the founders’ review. Rules and numbers are verified before public launch.

Chapter 56 · Roz Abernathy · Phases 1–3 · new draft

The down payment assistance maze

Maya Chen sends her running partner Roz: $64,000 a year, $4,200 saved and her mom moving in. The cheapest option at the closing table comes due in full when she sells, so Ellen lays out every column and lets Roz choose.

Rosalind (Roz) AbernathyBorrower · medical coder · first-time buyer
Bernadette AbernathyRoz’s mother · retired · moving in, not on the loan
Maya ChenReferrer · teacher · past client (Chapter 4)
Ellen QuinnYour mentor · veteran loan officer

All characters, lenders and records are fictional training material. New draft, pending the founders’ review. Rules and numbers are verified before public launch.

Chapter 57 · Tomas Reyes · Phases 1–3 · new draft

Not Yet, and Go

Darius King sends his engine partner Tomas, a Navy veteran with a 2023 VA loan at 7.625% and a mailbox full of refinance pitches. Which offer is real, which is a costume, and when is the honest answer “not yet”?

Tomas ReyesBorrower · firefighter/EMT, Navy veteran, VA loan at 7.625%
Ines ReyesTomas’s wife · reads the fine print
Marisol ReyesTomas’s sister · FHA loan closed April 2026
Darius KingReferrer · Tomas’s engine partner, from Chapter 6
Ellen QuinnYour mentor · veteran loan officer

All characters, lenders and records are fictional training material. New draft, pending the founders’ review. Rules and numbers are verified before public launch.

Learn · Rule cards

Every rule card in one place.

All the quick rules from the course, grouped by topic, with the source and where each one is taught. The chapters still teach each rule in context; this is the place to look one up. Guidelines change, so check the current source before you rely on one.

Mentor dashboard

Your mentees, and where to help.

Where each person you mentor is in the course, what they keep missing and where they’re stuck. Read their written answers and leave a review note. “View their course” shows exactly what they see, and nothing you click there changes their answers or progress. Their course progress, tasks and desk notes sync to their account, and that synced work is what you see here. Their contacts and the names behind their lists stay on their own device, so they never reach you.

Founders’ dashboard

Flags, learners and sticking points.

Everything testers flag, where every learner is, and the questions people miss most. Visible to admins only.

Loading the map…

Loading your day…

My Desk

Today

Everything due, in one glance. Clear it, log it, win the day.

Everything syncs to your account, so it follows you between devices and lessons. Your tasks and notes are private to you, and they never hold real names.

Loading…

Loading…

Free preview · free account

Step inside your first borrower file.

Chloe is renting and ready to buy her first condo, and she just asked you where to start. Work her file the way a real desk works it, with Ellen Quinn, a veteran loan officer, beside you. See exactly what the Field Guide teaches before you decide anything.

Base Camp · System guides

The software on a new loan officer’s desk.

The deeper guide behind each Base Camp group: what each system is, the setup that matters in week one, what new loan officers get wrong, and the exact questions to ask your manager. Steps you already have in Base Camp show here with the same checkbox, so there’s one checklist, not two.

Build Your Book

Knowing the loan is half the job. Building your book is how you own your market.

Twelve real situations every new loan officer runs into, from the agent who won’t call back to the past client who refinanced somewhere else. Each one comes with a mission, exactly who to go after, the words to say and the line you never cross. Start with the one you’re living through. There’s no week you’re behind on.

General training, not legal advice. Each week names the compliance line that governs it; your company’s policy governs and your compliance department decides.

My Desk

Referral tree

One good loan becomes a career. Watch every referral branch into the next one.

Your practice tree from the course. Two agents sent your first files; those clients sent friends, coworkers and family. Every box is a person, every line a referral, and every closed loan pays you.

Real lead? Start here

A real lead just called. Where do you start?

Search or pick the situation in front of you. You’ll get the rule to check before you call them back, the chapters that teach it, and the exact steps to review.

For teams

Training for your developing loan officers.

For owners, branch leaders and mentors at any brokerage or lender with newer loan officers and a mentor willing to coach. Request the free preview to see exactly what the course teaches before you decide anything.

See it before you decide

The free preview opens the Prologue and all of Chloe’s file, Chapters 1 and 2, exactly as a learner gets them, so you and your mentors can judge what it teaches. Full access and team pilots are available now. Pricing depends on your team and goals; Kim and Clayton walk you through it personally.

Request the free previewAbout the free preview

A short form. It goes straight to the two of us.

Who it’s for
  • Loan officers new to the industry who know the rules but still need help on a real file
  • Experienced originators moving into unfamiliar income, credit or property types
  • A mentor or team lead who’ll coach them through real files

What we are, and aren’t. We teach the craft, the daily discipline and the business — the part your best originator teaches one-on-one when they have the time. The files are written from a broker’s desk, where a loan officer works with more than one wholesale lender, but the judgment they teach — reading the file, checking the guideline, explaining the next step — is the same at a bank, a credit union or a retail lender. We are not a CRM, not a lead source and not a recruiter, and we store nothing of your company’s: no borrowers, no loan files, no pipeline. A learner’s own contacts and notes stay private to them. What we store, and what to keep out.

What loan officers get

Reps

Fifty-seven files before the real ones

Purchases, refinances, FHA, VA, jumbo, non-QM, condos, divorces, self-employed borrowers and reverse mortgages, across ten states.

Habits

A workflow to review with your team

Learners practice recording open questions, scheduling follow-ups and deciding when to ask for help. We show our own approach as a starting point for a conversation with their manager. Your team sets the workflow, within your company’s recordkeeping and compliance requirements.

Live help

A finder for real leads

When a real file gets complicated, the Scenario Finder points them to the exact chapters and rules before they call back.

What every learner produces
01A first-call file noteEvery fact labeled Reported, Open, Documented or Verified.
02A qualifying summaryIncome, debts, ratios and cash for each practice file, with the open items named.
03A focused document requestEvery request with a reason, an owner and a priority.
04A next-step planThe message to the borrower and a follow-up they can count on.
Guardrails
  • Every borrower and record is synthetic. No real consumer information.
  • Your company’s guidelines, compliance and lender requirements always control.
  • No company confidential information, branding or systems go into the materials without your approval.
  • Not a replacement for licensing education, underwriting or supervision.

Every loan file has a beginning, a middle and an end. So does learning to work one.

Why we built this

Real work rarely arrives as a multiple-choice question.

Licensing, company training, lender resources and mentors give new loan officers a foundation. Handling an incomplete or unfamiliar borrower file still takes practice, and most people get that practice on live borrowers.

A field guide, not another textbook

Field guides explain. Training companions give you reps. Scenarios supply the context. Together they help you spot patterns, ask better questions, understand why a document matters and know when to ask for help.

What a new loan officer actually hears

  • “I’m hourly, but overtime is a large part of what I actually earn.”
  • “I had a bankruptcy and I’m embarrassed about my credit.”
  • “My parents are helping with the down payment.”
  • “The Realtor needs an answer tonight.”
The founders

Between us: decades of experience teaching and originating, and one question we kept hearing from new loan officers: “Why didn’t anyone show me this?”

Clayton Chiavaroli

Clayton Chiavaroli

Co-founder · Originating since 2003

Clayton has originated mortgages since 2003, helping thousands of homeowners through the process. He’s worked nearly every kind of lending shop: small mortgage companies, a community bank, national retail lenders, and today as a broker originating residential and commercial loans.

That range is the point. He knows how the work looks from each side of the desk, and how much of it nobody explains to new loan officers. He holds a B.S. in Economics and Finance from Bentley University and speaks English, Spanish and Romanian. Off the clock, he’s reading or on a golf course.

Kimberly Smith

Kimberly Smith

Co-founder · Educator turned originator

Kim spent nearly two decades in classrooms in Oregon, Alaska and Florida, most of them teaching middle school math. She co-led professional development for her district’s math teachers, writing learning targets, rubrics and common assessments, served on curriculum-writing and math leadership teams, and took part in instructional coaching research with the Jim Knight Coaching Institute and the University of Kansas.

In 2016 she became a loan officer and found the same problem she’d spent her career solving: people being handed complicated material without being taught how to work through it. Since 2023 she has originated as a mortgage broker. She builds the Field Guide the way she built lessons, in small steps, with practice before pressure. She holds a master’s degree in Elementary and Middle School Education from Pacific University.

Nothing unusual usually requires a follow-up question.

Loading requests…

Get started

Request access

The Field Guide is for every loan officer: new to the industry, moving between retail, bank and broker, or ready to take on more complex files. And for the managers, mentors and trainers who develop them. Tell us a little about yourself. We read every request and reply personally, and loan officers we approve get an invitation to set up an account.

Add phone, company or NMLS ID (optional)
I’m interested in

Please don’t include borrower information. We use what you send only to reply to you.

Prefer email? Write to hello@loanofficerfieldguide.com.

My Contacts · Practice run

Your business starts with the people you already know.

Every loan officer’s business runs on relationships: family, friends, neighbors, past clients, agents and other professionals. Nobody teaches you how to organize them, or how to stay in touch without it feeling like a sales pitch. Practice on a sample book first, then do it for real in your contact system.

Step 1 · PracticeSort a sample book25 made-up contacts written as if they were yours, so you can tell how close each one is.
Step 2 · RhythmMatch each tier to a touchCall, text, email or social.
Step 3 · Practice daysWork the book for 10 daysLearn things, earn referrals.
Step 4 · For realSet up your contact systemHow to set it up⬇ Contact list template (CSV)
Step 1 of 3 · Sort the book
0points
0badges

My Desk

My Contacts

Your business starts with the people you already know. Here’s how to set them up in your company’s approved system, and keep the daily rhythm going there.

The Field Guide doesn’t store real people. Your contacts belong in the CRM, company phone or secure spreadsheet your company approved.

Build your list offline. Download the contact template, fill it in on your own computer with Excel, Numbers or Google Sheets, then import it into your company’s CRM, Google Contacts or Outlook. Most systems let you match the columns when you import. The Field Guide never takes the file back: real people belong in your company’s system.

⬇ Contacts workbook (Excel) Outlook import (CSV) Google import (CSV) Any CRM (CSV)

Loading your book…

Get started

Request access

For every loan officer, new or experienced, and the managers, mentors and trainers who develop them. Here’s what happens: send this short form, and Kim and Clayton will set up your free account and email your invitation, usually the same business day. Then you set a password and start. The preview is free, and no experience is needed.